Fed Rate Decision This Week: Why a Hold Is Likely and What It Means for Your Money
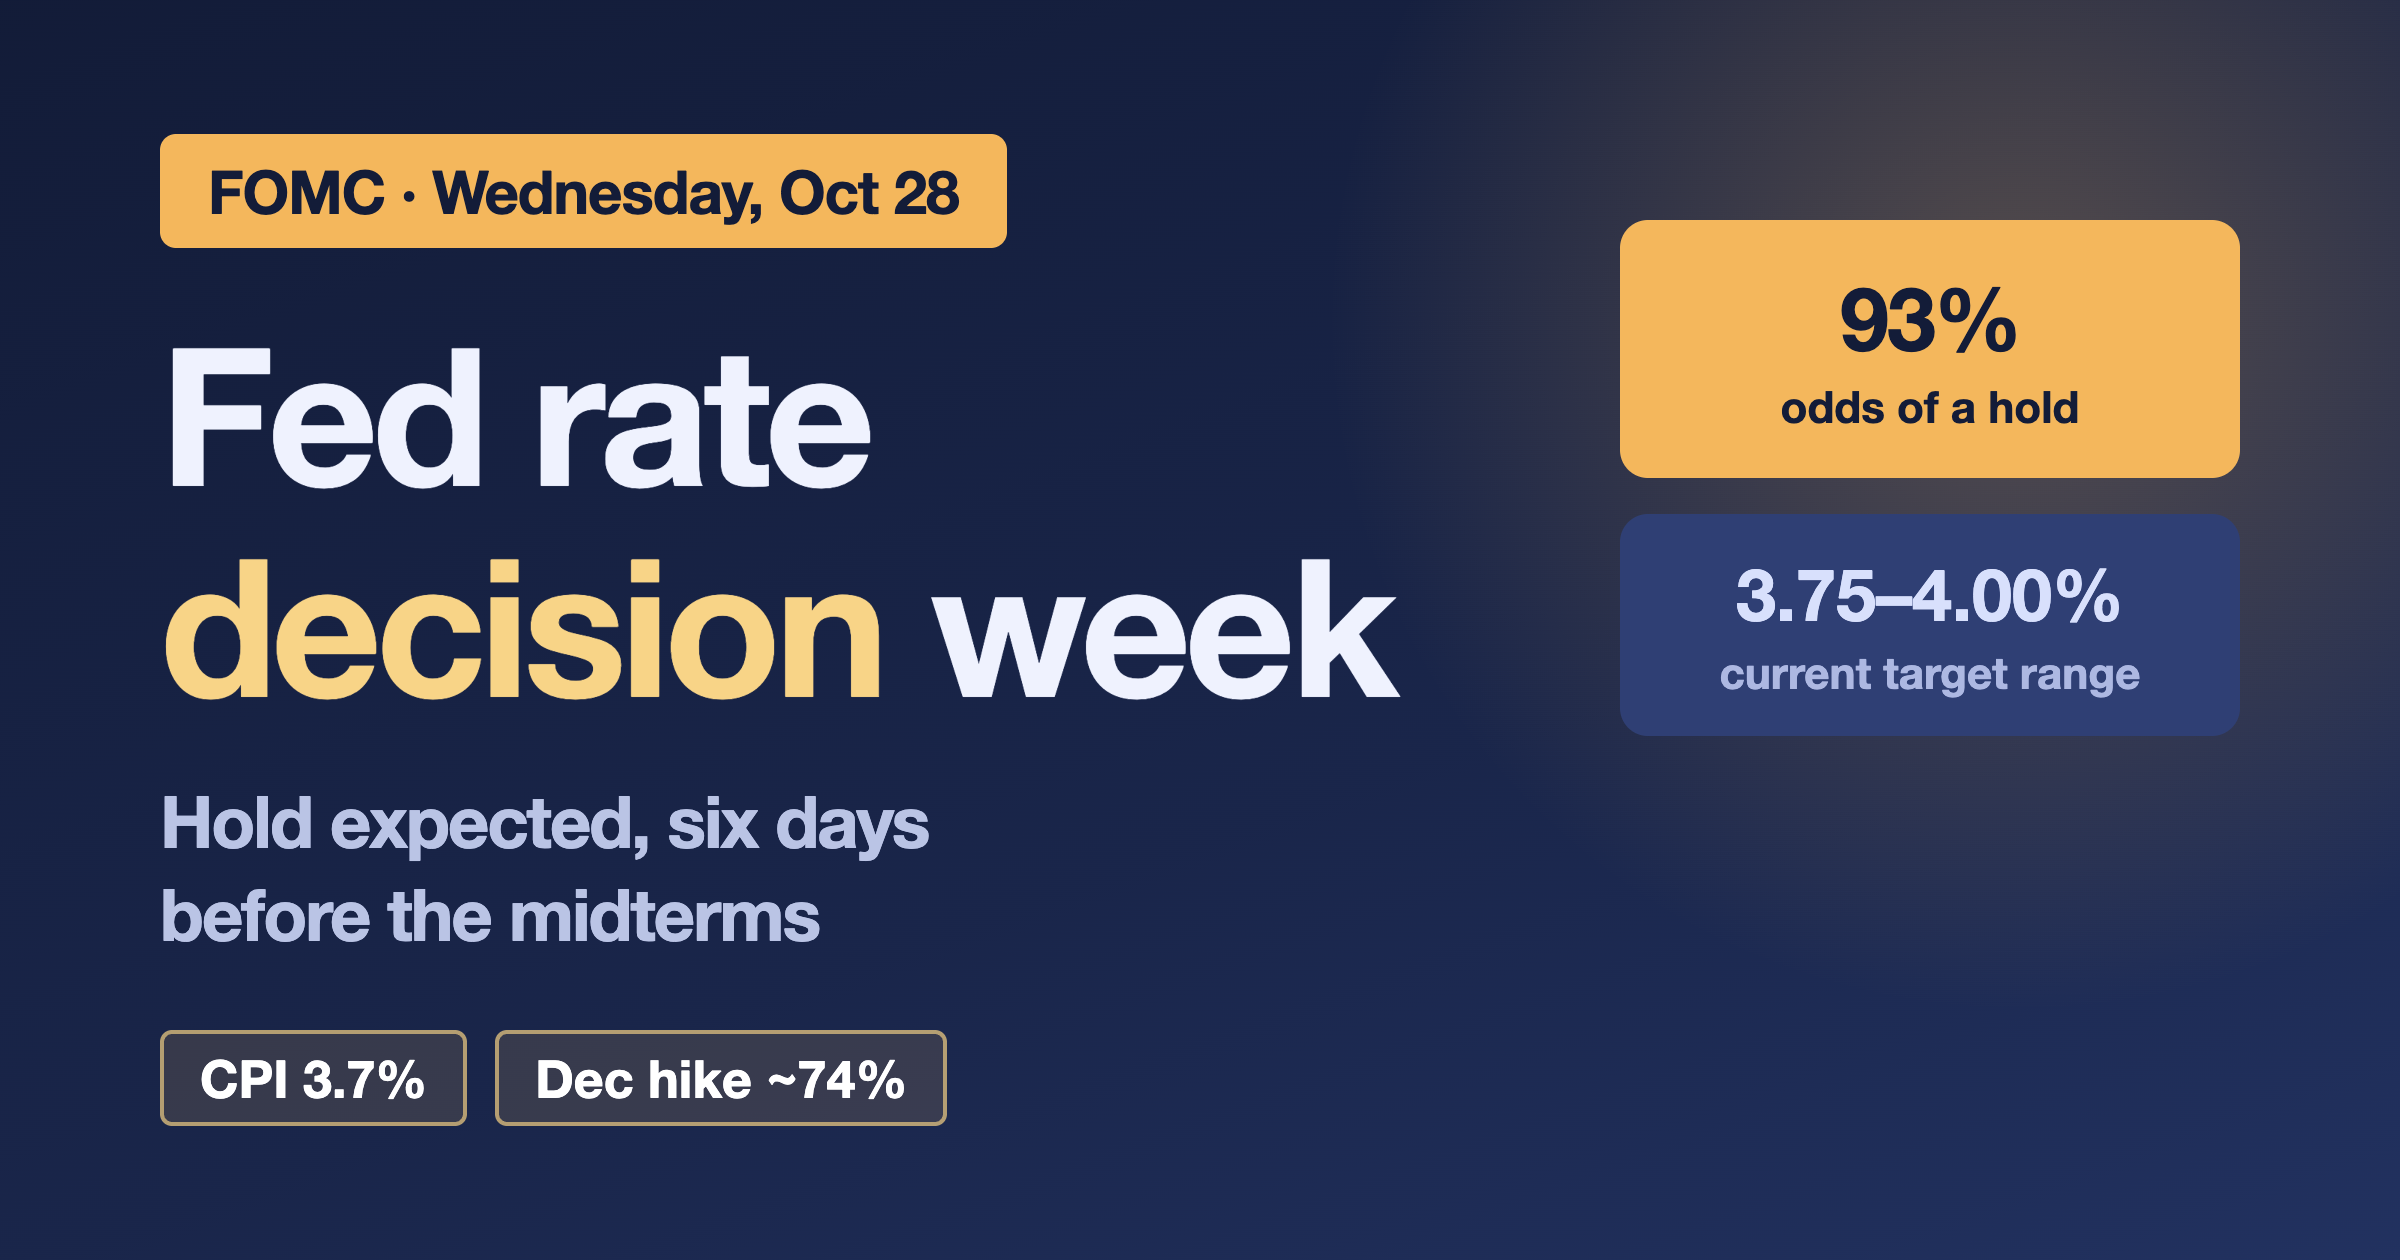
The Fed rate decision lands this Wednesday, October 28, at 2 p.m. Eastern. Six days later, Americans vote in the midterms. That timing is the whole story this week. On paper, inflation says “hike again.” The calendar says “don’t touch anything.” I read the September statement, the latest CPI report and the betting odds, and here is where things stand.
What the Fed decided last time
On September 16 the Federal Open Market Committee raised its target range by a quarter point, to 3.75 to 4 percent. The vote was 12 to 0. The statement called economic activity “solid” and said “inflation remains elevated.” It promised the move would “support a timelier return to the Committee’s 2 percent goal.”
Chair Kevin Warsh later described the hike as removing “a dose of accommodation.” In other words, the Fed thinks it had been too easy for too long. A central bank that just hiked usually does not go quiet unless something changes. So what changed? Honestly, not much, and that is the problem.
Then the September inflation report came in hot
The CPI release on October 14 was not pretty. Prices rose 0.6 percent in September alone and 3.7 percent over the past year. Core inflation, which strips out food and energy, was calmer. It rose 0.3 percent for the month and 2.6 percent for the year.
Gasoline did most of the damage. Pump prices jumped 9.1 percent in a single month and are up 34.2 percent from a year ago. Energy overall rose 5.2 percent. Shelter costs kept climbing at 0.4 percent. The headline number is well above the Fed’s 2 percent goal. Gasoline, though, is the kind of thing the Fed cannot fix with interest rates.
Right after that report, traders panicked a bit. According to a 24/7 Wall St. report, CME FedWatch briefly priced a 41.5 percent chance of an October hike, up from 22 percent the day before. Then cooler heads showed up.
Where the odds sit now
As of late Sunday night, prediction markets tracked by DeFi Rate put the odds of a hold at about 93 percent. A quarter-point hike sits at 7 percent and a cut at roughly 2 percent. These are prices on Kalshi and Polymarket, so they reflect what people betting real money think, not a poll.
| Outcome on Oct 28 | Prediction-market odds (Oct 26) |
|---|---|
| Hold at 3.75–4.00% | about 93% |
| Hike to 4.00–4.25% | about 7% |
| Cut | about 2% |
December is a different picture. The same markets price a hike at the December 9 meeting at roughly 74 percent. The market read is simple: the Fed wants to tighten again, just not in the week of an election.
Why the election matters more than people admit
The Fed insists it “does not factor the electoral calendar into its policy debates.” Maybe so. But since 1990 it has raised rates within seven days of Election Day exactly once, on November 2, 2022. Wednesday’s meeting is six days before November 3. UBS analyst Simon Penn called an October hike “politically untenable,” per the same report. He expects a December move instead.
I think that framing is right. A hold costs the Fed almost nothing. Core inflation is only slightly above target, and the Fed already signaled more tightening. A surprise hike six days before the midterms would hand every politician a talking point. In return the Fed would get maybe six weeks of extra tightening. That trade is not worth it.
There is one more reason to expect a quiet meeting. This is not a projections meeting. The Fed only publishes its “dot plot” at the March, June, September and December meetings, as its calendar shows. The last dots, from September, put the median year-end rate at 4.1 percent, and 16 of 18 officials expected at least one more hike in 2026, per Admiral Markets. That path still points to December.
What to actually watch on Wednesday
- 2:00 p.m. ET: the statement. Look for whether “inflation remains elevated” stays and whether anything new about gasoline or energy shows up.
- 2:30 p.m. ET: Warsh’s press conference. Any line about December is the headline.
- The vote count. September was 12 to 0. A dissent in favor of a hike would tell you December is nearly locked in.
- The balance sheet line. September’s statement said the Fed is “maintaining ample reserves.” Any change to that wording would be news.
What the Fed rate decision means for your money
Even a hold is not neutral. The September hike is still working its way into loan and deposit rates. Here is what the current numbers look like.
Mortgages
Freddie Mac’s weekly survey for October 22 put the average 30-year fixed rate at 7.32 percent. That is down 0.08 from the prior week but 1.13 points higher than a year ago. The 15-year sits at 6.68 percent.
My math: on a $400,000 loan, 7.32 percent means a payment of about $2,748 a month. At last year’s 6.19 percent it would have been about $2,447. That is roughly $300 a month, or $3,600 a year, for the same house. A hold on Wednesday will not undo that. Mortgage rates follow where markets think the Fed is heading more than any single decision, so the tone of Wednesday’s press conference matters more than the hold itself.
Credit cards
The Fed’s own consumer credit data shows the average credit card rate on accounts that carry a balance at 22.36 percent as of August. On a $6,000 balance, that is about $112 a month in interest, my math again. Another quarter-point hike in December would add only about $1.25 a month. The rate is not the real problem here. The balance is.
Savings and CDs
This is the quiet frustration. The FDIC’s national averages for October 19 show savings accounts paying 0.38 percent, money market accounts 0.63 percent, and 12-month CDs 1.76 percent. On $10,000, that is $38 a year in a typical savings account versus $176 in a 12-month CD, my math. These are national averages, so it pays to compare what your own bank offers against them.
Car loans
The same Fed data puts a 60-month new car loan at 7.54 percent. If the Fed does hike in December, expect new loan offers to drift up over the following weeks rather than overnight.
My read
The Fed will hold, say inflation is still too high, and leave December wide open. That is the boring outcome and the likely one. The interesting part is what Warsh says about gasoline. If he treats the energy spike as temporary, December gets softer. If he says it is feeding into expectations, December is a hike. For most households the advice is the same either way. Pay down card balances before they get more expensive, and move idle cash out of a 0.38 percent savings account.
The short version
The Fed meets October 27–28 and markets give a hold at 3.75–4.00% about a 93% chance, six days before the midterms. September CPI of 3.7% keeps a December hike (about 74% odds) on the table, so mortgage, card and CD rates are not coming down soon.
Facts and figures were checked against the sources below when this was written. Things change fast, so confirm with the official page before you act on anything here.
Sources
- Federal Reserve: FOMC statement, September 16, 2026
- Federal Reserve: FOMC meeting calendar
- BLS: Consumer Price Index, September 2026
- DeFi Rate: Fed decision odds (Kalshi/Polymarket)
- Yahoo Finance / 24/7 Wall St.: Oct 28 hike odds and election timing
- Admiral Markets: Fed rate decision October 2026
- Freddie Mac: Primary Mortgage Market Survey, October 22, 2026
- FDIC: National rates and rate caps, October 19, 2026
- Federal Reserve: G.19 Consumer Credit, August 2026